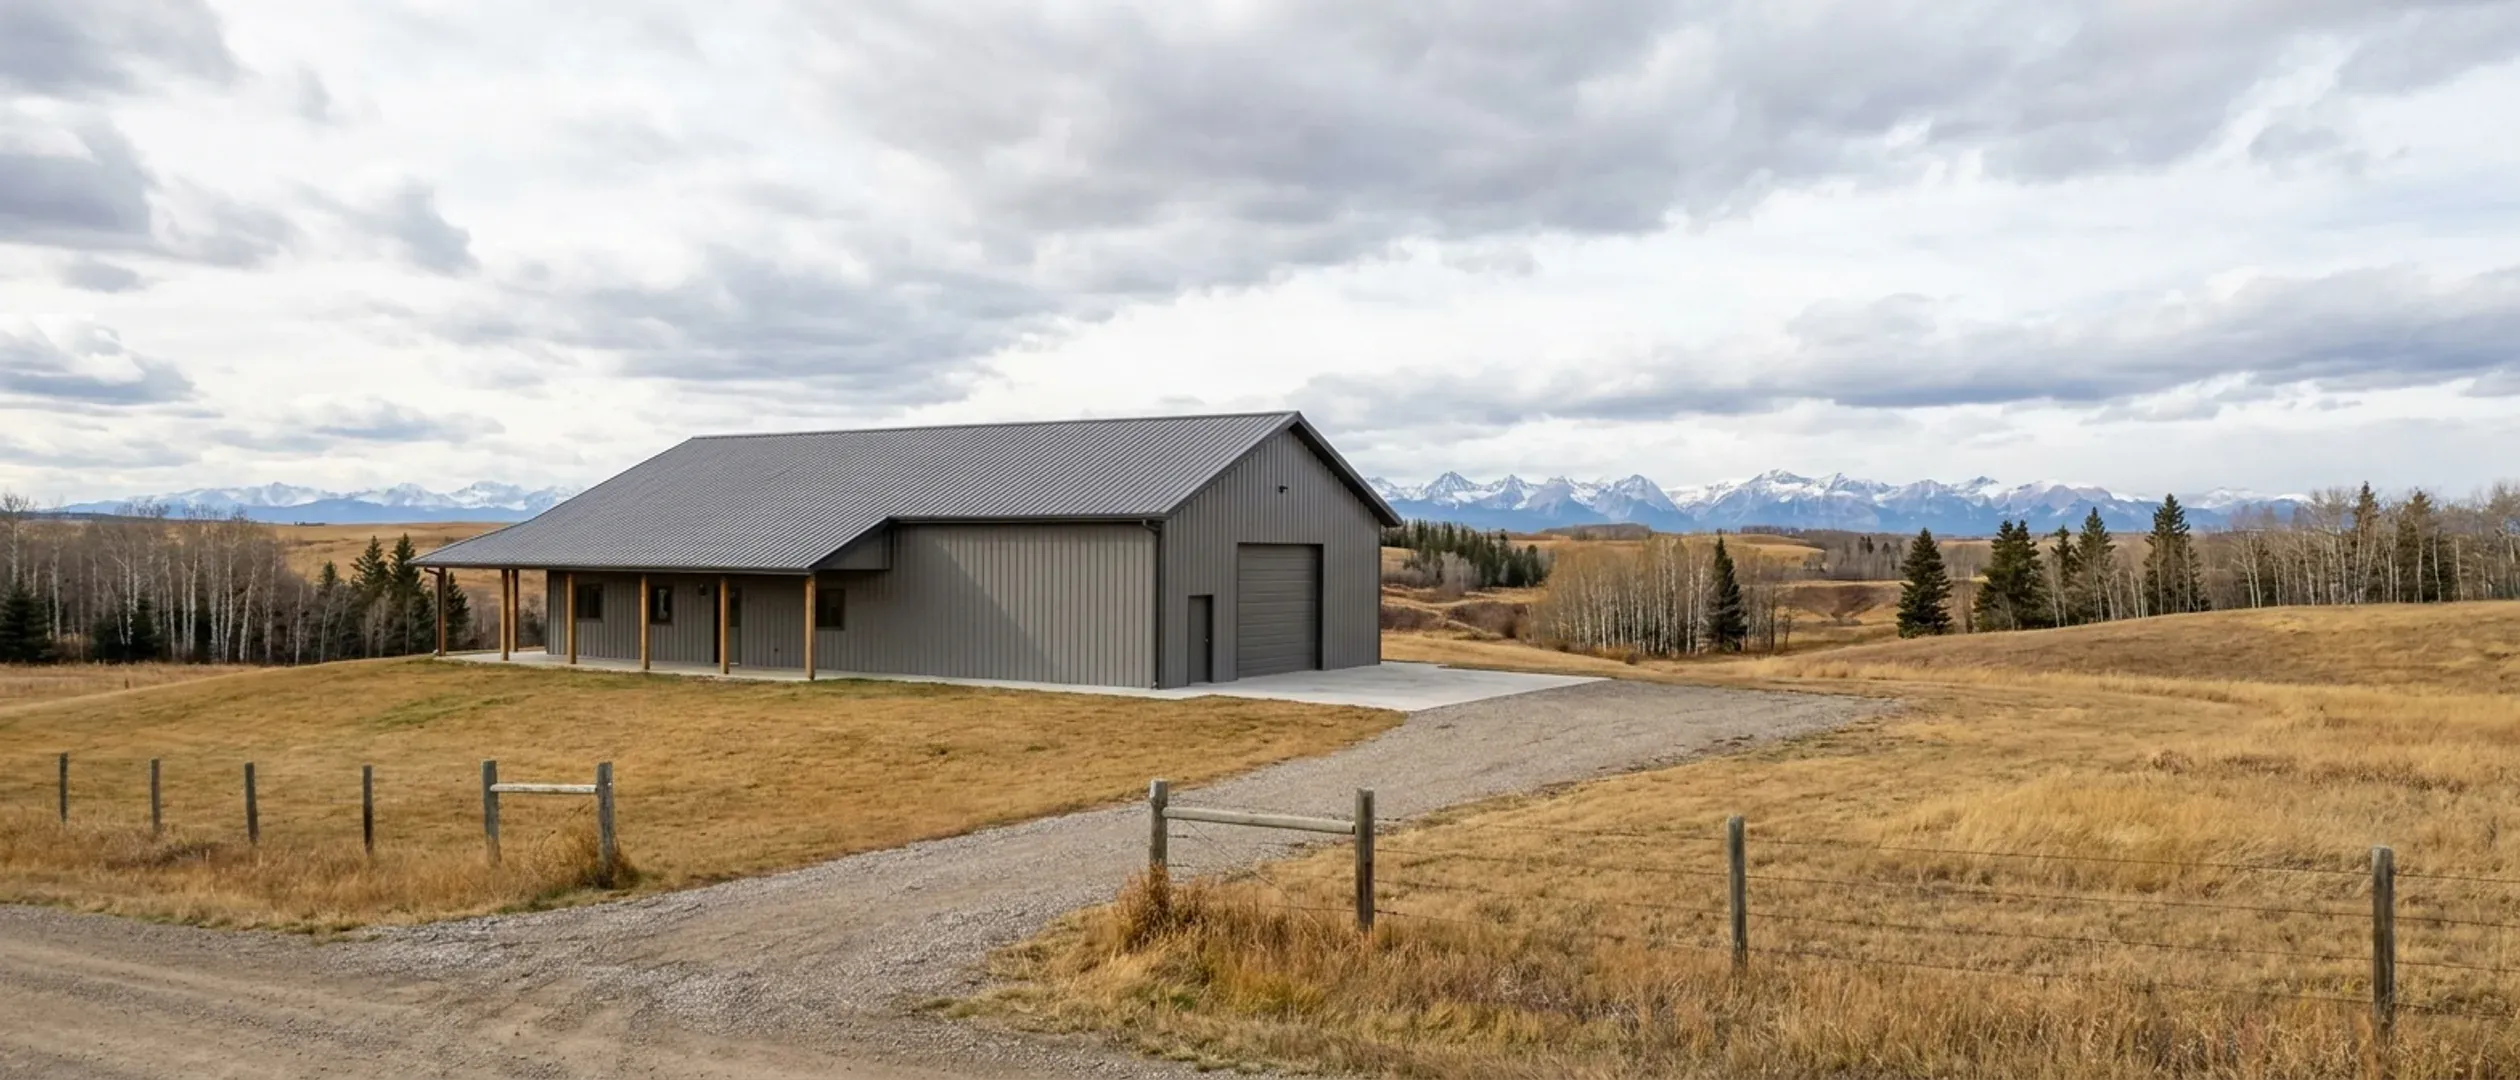
Financing and Insuring a Barndominium in Canada
There is no special barndominium mortgage in Canada, and there does not need to be one. A barndominium you live in is a house, and lenders finance it with the same construction and mortgage products they use for any new house. What changes is how easy it is to value, how the money is released while it is built, and what the lender and insurer want to see. This guide sets out the rules from CMHC, OSFI, FCC and the Government of Canada.
Figures on this page are cited third-party or government data, not a quote from Chinook Barndo Co..
Bottom Line Up Front
- A barndominium is usually financed with a construction (draw) mortgage. CMHC insures progress-advance loans for new construction, whether you build it yourself or hire a builder, and it uses the lower of market value or construction cost as the lending value.
- With less than 20% down you need mortgage loan insurance: CMHC requires 5% of the first $500,000 and 10% of the remainder, and insurance is not available at $1,500,000 or more. Every mortgage is qualified at the greater of your contract rate plus 2% or 5.25%.
- FCC lends to people with agricultural revenue. On a working farm it is a real option; for an acreage bought only to live on, a bank, credit union or mortgage broker is where to start.
How Do You Finance a Barndominium in Canada?
The lender is financing a house on a piece of land, and it looks at both.
A construction (draw) mortgage
Because there is no finished house to buy, the money is released in stages as the work is done. CMHC insures progress advances for new construction financing, and under its Full Service option CMHC validates up to 4 consecutive advances at no cost. Under Basic Service the lender validates the advances itself.
Owner-built or contract-built
CMHC's Improvement product covers both. For an owner-built home the borrower holds title to the land by the first advance and performs or manages the construction; for a contract-built home the borrower holds the land and has a contract with a single builder. Lenders set their own conditions on top of CMHC's.
What the property has to be
CMHC insures homes that are in Canada, suitable and available for full-time, year-round occupancy, and have year-round access. A seasonal cabin on a summer-only road does not qualify, and neither does a barndominium that cannot be reached in winter.
Preapproval is not approval
The Financial Consumer Agency of Canada notes that before a lender approves your loan, it will verify that the property meets certain standards, and that those standards vary from lender to lender. Get your plans and site in front of the lender early.
CMHC Mortgage Loan Insurance Rules
If your down payment is under 20%, the mortgage must be insured. These are CMHC's published rules.
Minimum down payment
CMHC requires a minimum down payment of 5% on a home costing $500,000 or less; above $500,000, 5% on the first $500,000 and 10% on the remainder. CMHC insurance is not available if the home costs $1,500,000 or more.
Premiums
CMHC's premium on a homeowner loan is a percentage of the total loan: 2.80% at 80.01% to 85% loan-to-value, 3.10% at 85.01% to 90% and 4.00% at 90.01% to 95%. The premium can be added to the mortgage. An amortization beyond 25 years carries a 0.20% surcharge.
30-year amortization on new builds
CMHC Home Start insures 30-year mortgages where at least one borrower is a first-time buyer or the home is newly built and not previously occupied, with the purchase price or as-improved value below $1,500,000. Its premiums run from 3.00% at 80.01% to 85% loan-to-value to 4.20% at 90.01% to 95%.
Qualifying ratios and credit
CMHC's maximum thresholds are a 39% gross debt service ratio and a 44% total debt service ratio, calculated at the greater of the contract rate plus 2% or 5.25%, and at least one borrower or guarantor needs a credit score of 600 or more.
New home warranty evidence
CMHC requires evidence that a newly built home is enrolled in a recognized new home warranty program wherever one is available, even if provincial law does not require it. For an owner-built home that is exempt from warranty, it asks for the occupancy permit or a third-party report from a qualified professional.
Energy-efficient homes
CMHC's Eco Plus product offers a 25% partial premium refund to borrowers who buy or build climate-friendly housing using CMHC-insured financing. A well-insulated barndominium may qualify; ask before you design, not after.
Appraisal and Lending Value
The most common financing problem with an unusual house is the valuation, not the borrower.
Lower of value or cost
For new construction, CMHC sets the lending value at the lower of the market value or the purchase price or cost of construction, and the down payment is based on that figure. If an appraiser values the finished barndominium below what it cost to build, the gap comes out of your down payment.
Why comparables matter
An appraiser values a house against recent sales of similar houses nearby. A rural barndominium with a large shop may have few direct comparables. Detailed plans, a specification and a written construction budget give the appraiser something concrete to work from.
Uninsured mortgages are stress-tested too
With 20% or more down you can avoid mortgage loan insurance, but OSFI requires federally regulated lenders to qualify you at the greater of the contract rate plus 2% or 5.25%. The lender's own property standards still apply.
FCC Financing for Farm Properties
Farm Credit Canada is a lender to agriculture, not a general home lender.
Who FCC lends to
To apply for a loan with FCC you must be a Canadian citizen or permanent resident, of the age of majority, and have revenue from activities involving agriculture or a business related to agriculture. A family buying an acreage only to live on does not meet the last test.
What FCC offers on land and buildings
FCC's land and buildings financing lists deferred payments, interest-only payments and extended disbursements, and lets customers schedule payments around growing cycles, off-farm income and during construction. If the barndominium sits on a working farm, ask FCC how it treats the residence alongside the farm buildings.
Land values are rising on the Prairies
FCC's 2025 Farmland Values Report puts the average change in cultivated farmland values at +11.4% in Alberta, +9.4% in Saskatchewan and −1.7% in British Columbia. A rising land market helps an existing owner's equity and raises the price of a new parcel.
Using Your Savings: HBP and FHSA
Two federal programs let you use registered savings to build, not just to buy.
The Home Buyers' Plan
The Canada Revenue Agency's Home Buyers' Plan lets you withdraw from your RRSPs to buy or build a qualifying home. The current withdrawal limit is $60,000, and it is repaid to the RRSP over time.
The First Home Savings Account
An FHSA lets a first-time home buyer save to buy or build a qualifying first home tax-free, up to certain limits; the CRA sets first-year participation room at $8,000. You can use the HBP and an FHSA for the same qualifying home if you meet the conditions for each.
Insuring a Barndominium
Home insurance is a separate product from mortgage loan insurance, and your lender will require it.
What insurers price
The Insurance Bureau of Canada says a home's size, how and where it is constructed and the value of your contents significantly affect what you pay. Tell the insurer the construction type, steel or post-frame, at the quote stage.
Distance from fire protection
The IBC notes that a property far from a fire hydrant or fire station may cost more to insure. Most barndominiums are rural, so get a quote for your actual parcel before you finalize the budget. Wood stoves also affect the availability and affordability of home insurance.
Replacement cost, not market value
The insured amount should match what it would cost to rebuild. In a 2024 release the IBC reported Statistics Canada data showing a 73% increase in residential building construction costs in Alberta since 2019. Insure to today's rebuild cost, not to what the land and house might sell for.
Reading this because you are weighing a build? The next step is a plan drawn for your program.
Province by province
Alberta: warranty and lenders
Every new home in Alberta must be registered and carry warranty coverage. An owner-builder with an Owner Builder Authorization can go without warranty, but gets a caveat on the land title, and the province notes that financial lenders may require warranty. Settle the warranty question before you apply for the mortgage.
Saskatchewan: PST on the insurance premium
CMHC lists Saskatchewan among the provinces that apply provincial sales tax to the mortgage loan insurance premium, and the sales tax cannot be added to the loan amount. Budget it in cash at closing.
British Columbia: warranty insurance
Every new home built by a licensed builder in B.C. must be covered by third-party home warranty insurance: 2 years on materials and labour, 5 years on the building envelope and 10 years on structure. CMHC asks for evidence of warranty enrolment on newly built homes where a program exists.
Can you get a mortgage for a barndominium in Canada?
Does CMHC insure barndominiums?
What is a construction draw mortgage?
How much down payment do I need to build a barndominium?
Can I get an FCC loan for a barndominium?
Is a barndominium harder to insure?
Can I use my RRSP or FHSA to build?
Do I need a 30-year mortgage?
Questions answered? Tell us what you want to build and we will put real numbers against it.
Sources
- CMHC — What is CMHC Mortgage Loan Insurance? (minimum down payment and the $1,500,000 limit)
- CMHC — Premium Information for Homeowner and Small Rental Loans
- CMHC — CMHC Home Start (30-year amortization, debt service ratios, progress advances)
- CMHC — Mortgage Loan Insurance: CMHC Programs Fact Sheets (PDF; CMHC Improvement, construction arrangements, warranty evidence)
- OSFI — Minimum qualifying rate for uninsured mortgages
- Financial Consumer Agency of Canada — Getting preapproved for a mortgage
- FCC — Loan Essentials (eligibility)
- FCC — Land and Buildings financing
- FCC — 2025 Farmland Values Report
- Canada Revenue Agency — The Home Buyers' Plan
- Canada Revenue Agency — First Home Savings Account (FHSA)
- Insurance Bureau of Canada — How home insurance rates are set
- Insurance Bureau of Canada — Pressures have been mounting on home insurance premiums as residential building construction costs soar by 66% since 2019
Keep reading
The pages that answer the next question this one raises.
How much does it cost to build a barndominium in Alberta?
The construction figures your lender will want to see justified.
Read itWhat size barndominium can you build for your budget?
Budget to square footage, with the qualifying rules applied.
Read itCan you build a barndominium in Canada?
Permits, codes and warranty rules in Alberta, Saskatchewan and B.C.
Read itTurnkey builds
One contract from site work to occupancy.
Read itWant a real number instead of a range?
Start the survey and tell us about your land and what you want to build. Include the rural municipality or county and the legal land description if you have them, because the local land use bylaw, the septic system and the water supply change the budget more than the building does. The survey costs nothing.